
Today’s world of mortgages is made up by two sorts of loans government backed loans and government insured loans. Government insured loans are hugely popular. The FHA Loan is the benchmark government loan appealing to many due to its flexible guidelines and lower down payment options. Here is one pitfall you need to know if you are married….
Unlike government backed loans such as Fannie Mae loans the FHA views married couples jointly. This means joint responsibility and joint liabilities. FHA Loans require the lender pulls credit on the debt of the spouse even if the spouse is not on the mortgage. Let’s say you have a husband and wife scenario. Husband is on the loan and has a healthy credit score manageable debts and a solid job. Spouse does not. So she is not on the mortgage application. Lender pulls his credit on both the husband and the wife in this scenario because the FHA requires it. If the wife has separate debt beyond the obligations of the anchor borrower those obligations will be counted into the debt to income ratio.
This requirement has no bearing on the transaction being a refinance or purchase. The debt of the spouse will always count against the borrower even if they are not on the loan. The reason this can become problematic is because of the debts of the spouse exceed the anchor borrowers obligations that can drive up the debt to income ratio lowering borrowing power in the process. This could hurt one’s ability to perform on a purchase contract or forgo a refinance opportunity.
If you are single this requirement does not apply. If you are single, but engaged this requirement does not apply. When you become legally married is when the guideline kicks in and when the debt of both spouses is required for qualifying for the mortgage loan.
Mortgage tip: if one of the spouses is applying for a mortgage for another property in a sole and separate transaction, a quit claim deed at escrow is going to be required for the married spouse signing off on the transaction.
If you are married and plan to apply for an FHA Loan plan on lender looking at both yours and your spouse’s credit reports. If your spouse has credit that otherwise hurts the financial profile consider changing loan programs such as switching from an FHA loan to a conventional loan. A conventional loan only requires 1.5% more in down payment than FHA and does not have that requirement which may improve borrowing chances. If you are not married and plan to get married and you know what the financial picture of your spouse is buy the house first then tie the knot.
Looking to get a mortgage? Get a free quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
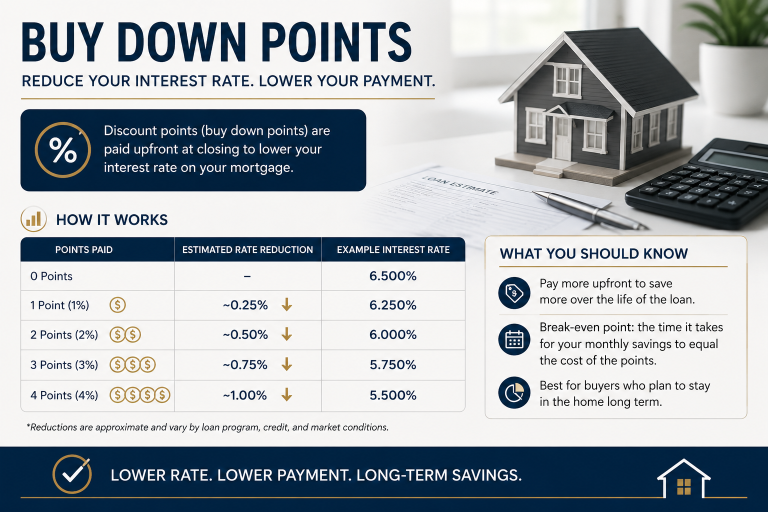
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!