
If you’ve ever applied for a mortgage, you’ve probably wondered why lenders sometimes ask for the same documents more than once—or even request new paperwork late in the process. While it can feel frustrating, there are good reasons these document requests pop up at different stages of a loan file.
Why Duplicate Requests Happen
A mortgage application passes through several hands before it reaches the closing table. Your loan officer collects initial paperwork, but processors, underwriters, and quality control teams all review the file. Each step can uncover the need to verify or update documents. For example, if you provided a bank statement at the start of the application and the statement cycle has since closed, the underwriter may need the next month’s statement to show your funds are still available.
Time-Sensitive Documents Expire
Some items have strict expiration dates. Credit reports, pay stubs, bank statements, and even employment verifications must be current when the loan closes. A pay stub that was valid when you applied might be too old by the time underwriting issues the final approval. Lenders ask again not because they lost your paperwork, but because federal and investor guidelines require updated proof.
Changing Financial Circumstances
Life doesn’t stand still during a mortgage transaction. You may receive a bonus, pay off a credit card, or take on a new debt. Any of these changes can impact your debt-to-income ratio or credit profile. Underwriters need the most current information to ensure you still meet program requirements, whether you’re applying for a loan program like FHA, VA, or a conventional mortgage.
Multiple Layers of Review
Even after initial underwriting, many lenders perform quality-control checks before funding. These internal audits confirm that the file meets both investor and regulatory standards. If anything looks unclear or out-of-date, the quality-control team may request documents you already submitted, simply to double-check accuracy and compliance.
How to Make the Process Easier
- Provide complete documentation the first time. Missing pages or unreadable scans are common reasons for follow-up requests.
- Keep your records handy. Maintain quick access to updated pay stubs, bank statements, and tax returns in case they are needed again.
- Avoid major financial changes, like opening new credit accounts, while your loan is in process.
- Respond promptly to lender requests. Quick responses help prevent delays in underwriting and closing.
Bottom Line
Repeated or new document requests are a normal part of mortgage lending. Lenders must verify your financial picture is accurate and current right up until closing. While it can feel like unnecessary repetition, these checks protect both you and the lender, ensuring the loan meets all guidelines and is approved without last-minute surprises.
Looking for a mortgage? Get a complimentary rate quote now!
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
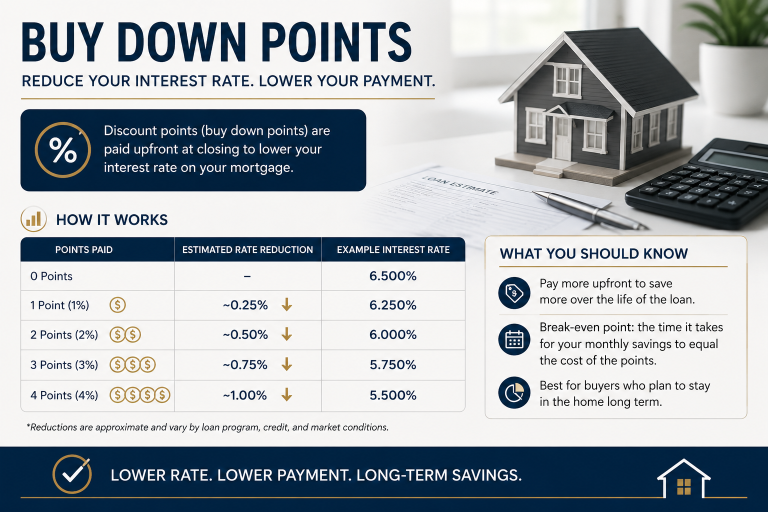
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.

blog idea
Does to make sense to cash refinance to consolidate debt? How to use child support…
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!