
Unlike an auto loan, a lease is a short debt that contain a future pay off. Here is why a lease can hurt your chances of getting a mortgage…
Lenders look at the minimum monthly obligations that you pay on your debts. They take those minimum payments and add those to a proposed total mortgage payment reflective of principal, interest, taxes, insurance and PMI (Private Mortgage Insurance) and then divide that number by your gross income. This creates your debt to income ratio, which is a barometer that lenders use to determine your ability to repay.
Car loans can be especially detrimental to your ability to buy a home and qualify for a mortgage because the minimum payments on car loans can be very expensive relative to mortgage payments and adversely affect your debt-to-income ratio. $500 per month on a car loan is nearly equivalent to $100,000 in spending power when buying a home. It’s literally that powerful, and because of that, buying a new car could seriously harm one’s ability to qualify for mortgage financing.
A car lease is something else entirely. The reason a car lease can be problematic is because the unlike a car loan, a car leases’s total obligation includes the balance of the lease term, in addition to the final buyout of the lease (what you must pay if you don’t return the vehicle at the end of the lease). This is where things can become problematic. Let’s say to qualify for your mortgage, you need to pay off debt to bring down your debt-to-income ratio. If you are doing a refinance and have enough equity in your home, you may even be able to pay off your consumer debt as part of your refinance. Under this scenario, let’s say you have a lease that shows a balance of $8,000 on your credit report and a monthly payment of $300 per month. If that was a car loan where you are truly financing the entire cost of the car it would be as simple as paying off the $8,000 in exchange for freeing up $300 per month of borrowing power. That dynamic changes when you have a lease because you’d have to pay off the lease portion as well as the balance of the car after the lease obligation. This would require more cash or converting your remaining lease balance to an auto loan.
If possible, pay off your other consumer obligations first and then work to pay off the car. Alternatively, you can always finance the car under a traditional auto loan instead of leasing the car, that way you can cherry pick which obligations to pay off to qualify faster, while improving your borrowing position to better your mortgage chances.
Looking to get a mortgage? Get a free quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
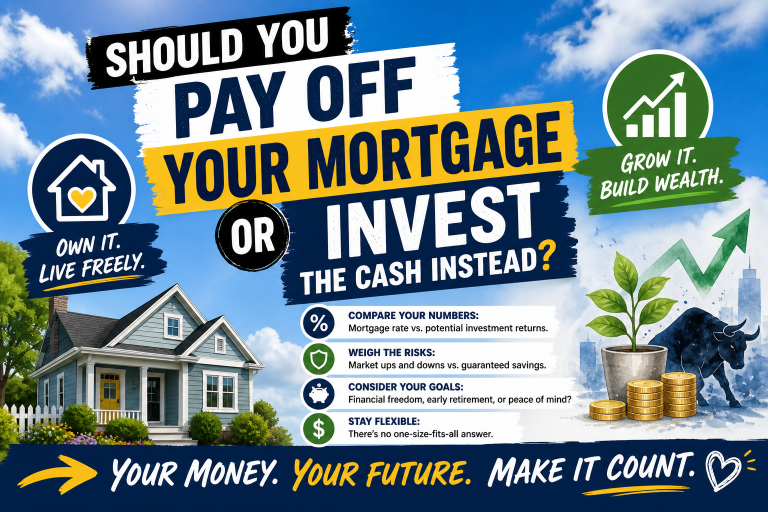
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!