
Getting a mortgage in 2018 there is a bureaucratic and compliant process with a significant amount of paperwork involved. Following is some tips on various loan programs available in the marketplace you may not know…
Conventional mortgages they will go up to a debt to income ratio of 50%. Here is the kicker if your credit score is extremely good 764 examples or above your front-end housing payment and debt to income ratio can both be as high as 49%. Simply put 49% of your monthly income can go towards a housing payment. This is significant because on other loans such as FHA for example the front-end housing payment cannot exceed approximately 44% of your monthly income.
On a conventional mortgage you can get your payment offset that another party makes so long as they are on the note and make the payment directly to the creditor and have for the last 12 months and the payment comes from a non-joint bank account.
Arm’s length transactions involve involve no relationship between buyer and seller. In a divorce buyout situation or in a family purchase situation there is a relationship between the parties which would constitute what’s called a non-arm’s length transaction. Non-arm’s length transactions are eligible loans that can go through however it’s going to require careful planning and expertise on the side of the lender to make sure they properly package file so it will pass through the examination of the underwriter
If you have an alimony payment and are getting a conventional mortgage here is some information that may help you get qualified… alimony now comes off income and is not counted as a debt. This is huge for borrowing power because it allows you to qualify for a larger mortgage and it lowers your debt to income ratio in the process. Child support however is counted as a monthly obligation like a car payment on both conventional and an FHA Loans. FHA and conventional loans both carry this unique and helpful viewpoint on alimony payments.
VA loans will require you to provide a monthly budget when getting final mortgage loan approval of how you’re going to manage that mortgage payment with the rest of the expenses and dependents if you have any in your life. VA may also require a water test when financing a property with a private well. VA Loans must clear the pest report on a purchase transaction cannot be paid for by the buyer at all and any section one termite damage can be specifically paid for by the buyer. On a refinance borrower pays for both report and work to be completed.
Not sure how or if these may apply to you? Get a no cost quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Does a Cash-Out Refinance Make Sense to Consolidate Debt?
A cash-out refinance can simplify high-interest debt, but it also turns unsecured balances into debt secured by your home. Here is how to decide if the math and the risk make sense.
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
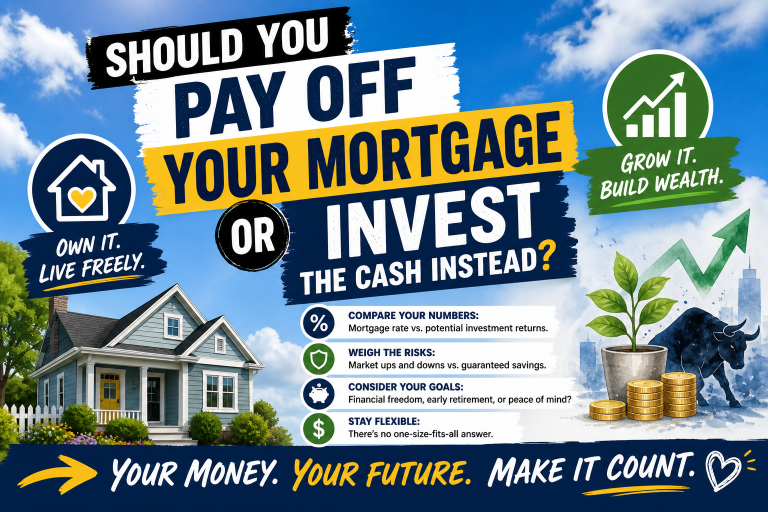
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!