
As mortgage rates continue to remain flat, it might not be a bad thing to consider really weighing out both options of getting a home equity line of credit or doing a Cash out refinance for that home improvement project or debt consolidation you have been thinking about. If you’re looking to pull money out of your house, consider your options first…
Home equity lines of credit are low cost to acquire sometimes no cost. If you ever close out the home equity line of credit you may incur an early closure fee. A home equity line of credit is effectively an enormous credit card tied to your house. You only pay interest on any present balance which means that it can sit there with no balance as a safety cushion, if you ever need to borrow money it is at your disposal.
Any payment that you make on the home equity line of credit for the first 10 years is interest only. Meaning your balance will never go down unless you make an overage payment and the additional money that you pay beyond your interest only payment goes toward principal. These loans are also variable rate tied to the prime rate.
Mortgage tip: these loans are no longer tax deductible.
Cash-out refinancing your first mortgage instead as an alternative to a home equity line of credit might not be such a bad thing. The closing costs might be about 1% of your loan amount maybe depending on your area and specific location. The interest rate is higher, but also is tax deductible. A 30-year mortgage also means having a lower payment for your debt. If you were to compare a fixed rate 30-year term to a home equity line of credit plus a first mortgage you might come to find that the payments for both are about the same or maybe as little as fifty bucks a month more (in some cases) for the comfort of having a long-term fixed-rate loan.
Most consumers would probably stand to benefit by being able to deduct more interest as a byproduct of cash-out refinancing their home to fix up their house or doing a debt consolidation for example then they would taking a home equity line of credit that is not tax-deductible and has a variable payment associated with it.
Therefore, it is critical to work with an experienced lender who can walk you through the ins-and-outs of deciding whether a fixed rate mortgage makes sense or whether home equity line of credit is a more suitable choice for you and your payment and cash flow objectives.
Looking to refinance? Get a no cost quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Does a Cash-Out Refinance Make Sense to Consolidate Debt?
A cash-out refinance can simplify high-interest debt, but it also turns unsecured balances into debt secured by your home. Here is how to decide if the math and the risk make sense.
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
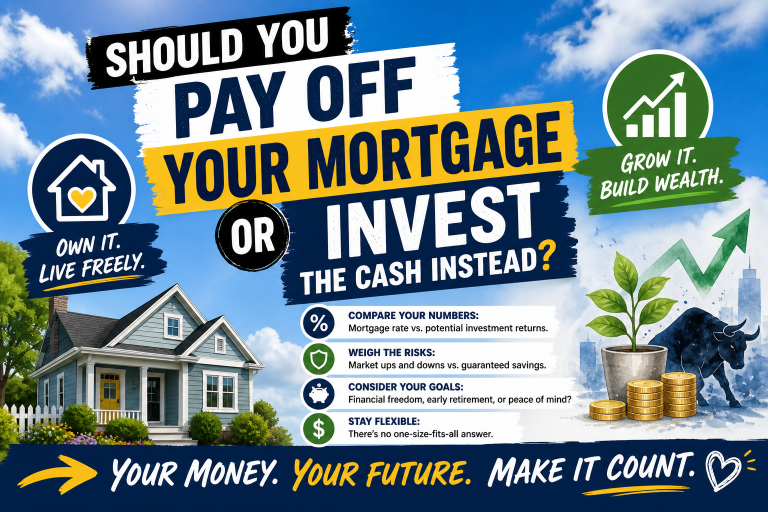
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!