
A bankruptcy can possibly be a detrimental blow to your mortgage chances if it’s not handled in the right way. Following is what you should take into consideration if you have a bankruptcy in your past or will be filing an upcoming bankruptcy…
First things first for our purposes we are discussing a Chapter 7 bankruptcy which is the full stripping of all your personal obligations. Contrary to popular belief you cannot discharge a mortgage. The mortgage loan tied to your primary home cannot be discharged in bankruptcy court.
If you are filing an upcoming bankruptcy but it is not yet been filed do the mortgage first. Even if you must pay a premium such as private mortgage insurance on an FHA loan for example that is a far better opportunity than having to wait potentially two years which otherwise would be the outcome on an FHA loan anyway after the bankruptcy discharge date.
If you have a bankruptcy in your past this is where things can become potentially problematic. Let’s say you have a mortgage on your primary home and you’ve successfully discharged bankruptcy and you’re now passed the two-year waiting mark. That mortgage that you had assuming it’s with an institutional lender no longer reports on your credit report. You still have the obligation to pay the payment each month, but it doesn’t report on your credit report. The credit report reports any payment history. The
The Bk does not report on your credit report after a chapter 7 as result the lender does not initially have your payment history which means that it’s super critical to continue to make your mortgage payments on time. If you have any mortgage lates in the last 12 months, 30 days overdue or more, getting a loan is going to be extremely tedious and it may not close escrow. You must have at least a 12-month clean payment history for getting a mortgage with an exception on one 30-day mortgage late in the last 12 months.
In other words when you’re going through the bankruptcy process make sure that if you are going to be doing any type of home financing mortgaging in the future that you I have a 12 month clean payment history and that you know what date the payment is due and you put it on autopilot so you don’t miss any payments.
Payment history when there is a bankruptcy in the past becomes even more financially crucial because the lender is judging your future ability to make payments going forward and the only way they can do that is based on your previous history. Keep that in mind next time you’re looking for mortgage financing.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Does a Cash-Out Refinance Make Sense to Consolidate Debt?
A cash-out refinance can simplify high-interest debt, but it also turns unsecured balances into debt secured by your home. Here is how to decide if the math and the risk make sense.
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
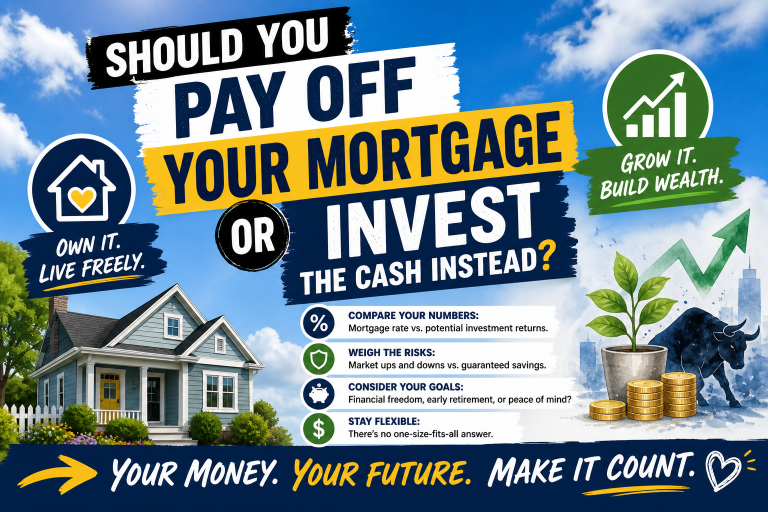
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!