
This local county housing market continues to evolve and show strong signs of growth and appreciation. Here is what you need to know if you are going to be buying a house in 2018…
Two things to watch for is interest rates and home prices. Both heavily can affect your ability to borrow and ultimately, you’re spending power.
Interests rates could rise from the low fours to the mid fours by summer 2018. A .5% change in interest rate on a loan for $450,000 is approximately $130 per month.
The big elephant in the room to be concerned about is housing prices. A house for $550,000 in January 2018 could easily be $595,000 by May 2018. Using a 20% down payment would change the mortgage payment just over $200 per month. If you’re doing a house purchase with less than 20% down that has monthly PMI built in for example you’re looking at a payment change of upwards of $245 a month more.
The longer you wait to purchase a house the more you are forced to save to offset having to pay a higher price with today’s dollars than future dollars. If your home buying plans is on the longer term (two years out or longer) you want to be saving somewhere between 10-12% of your pretax monthly income. If your home buying plan is within 12 months, you want to be saving 18-20% of your monthly pre-tax income.
It might make sense to start looking for a house sooner if the current market continues in the trajectory that it is currently going in. Here is why- in a rising market you will have market forces working for you i.e. potentially more home appreciation in your property and your ability to drop the monthly PMI becomes within your grasp sooner not to mention the substantial tax advantages.
Looking to get a mortgage? Get a quote now– its fast and simple.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
What to Know About Getting a Mortgage Loan in a Community Property State With FHA or VA Financing
In a community property state such as California, a non-borrowing spouse’s debts can still affect FHA or VA mortgage qualification. Here is what buyers need to know.
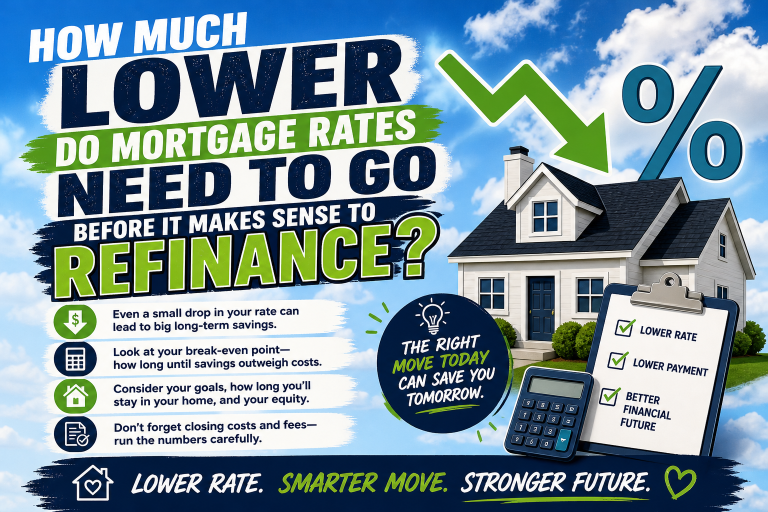
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
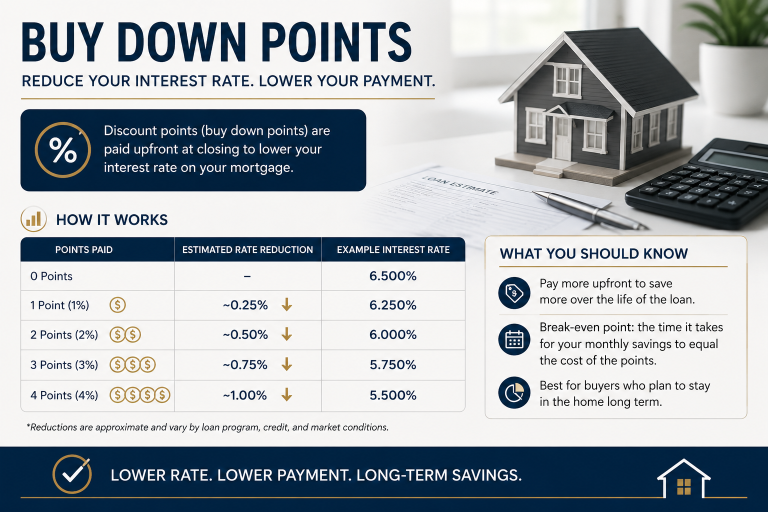
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!