
The Federal Housing Finance Agency which oversees loans bought by Fannie Mae and Freddie Mac announced to change to the conforming loan limit last week. Here’s what the change means for you…
Every year the Federal Housing Finance Agency releases its loan limits for the next year. Over the last 4 years, the agency has increased the loan limits nationwide. The loan limits are particularly of importance to the lifeblood of the housing market because it dictates what loans can be bought and sold by Fannie Mae and Freddie Mac.
The national conforming loan limit increase from $484,350 to $510,400 represents more windows of opportunity for homeownership. The most lucrative financing in terms of rates and fees and underwriting are traditionally for loans up to the conforming loan limit.
The increase by $26,050 to $510,400 means the difference between getting a conforming loan and what’s called a Conforming High Balance Loan. A Conforming High Balance Loan can be used to buying a home or refinancing a home on a bigger loan amount while still being considered a conforming loan. This change is a game-changer for a family’s desiring to borrow money on slightly bigger mortgages going forward in the year 2020.
Using Sonoma County, California as an example the conforming loan limit is $510,400 the maximum high balance conforming loan limit remains the Same at $704,950 for a single-family one unit property so it is still attainable to get a conforming loan up to the maximum high balance loan limit. Anything beyond that loan limit becomes a Jumbo loan which is an entirely different type of mortgage classification which typically, but not always comes with tighter scrutiny and more supporting financial documentation.
The trend that the Federal Housing Finance Agency is continuing to uphold supports a system in which more families will be able to borrow money with bigger loan sizes. In support of this, all residential mortgage loans still require an ample supply of cash, credit, and income. Make no mistake when it comes to applying for a mortgage you still meet the ATR requirements which is your ability to repay.
Looking for a mortgage? Get no cost quote now!
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
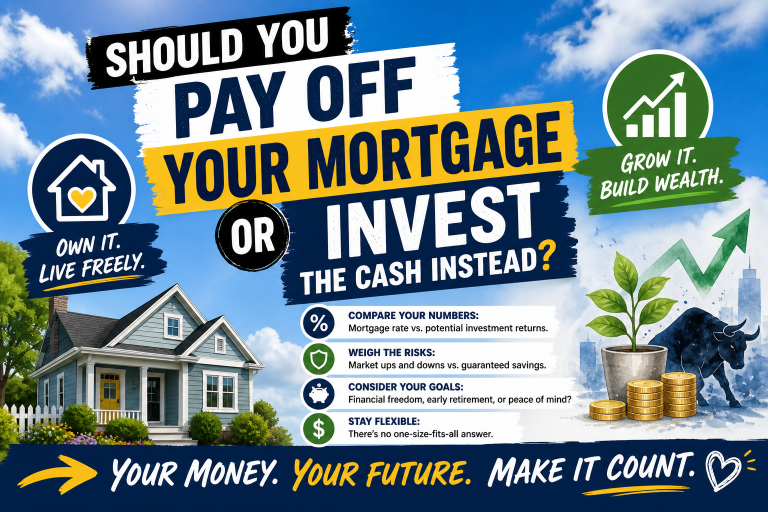
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!