
Fannie Mae and Freddie Mac have a very conservative calculation when it comes to using rental income to qualify. Here’s what you need to know if you’re getting an FHA mortgage and you have mortgaged rental property…
Fannie Mae and Freddie Mac’s mortgage calculation of use net income is super conservative and will make your mortgage on your rental property worse from a debt to income ratio perspective. Let’s say you’re renting out your property for $3,000 per month. After the calculation you may end up being $1,700 a month based on your taxes, Insurance, utilities and depreciation. If you need that rental income to qualify their analysis just decreases your borrowing power.
The FHA recently changed their interpretation of how lenders calculate income if you are seeking financing and have a mortgaged rental property. The lender is now only required to go to your schedule E of your federal income tax return (where you are required to identify and claim rental property) they take the net income of that rental property income and they simply add back depreciation to the net figure and divide that number by 12. This benefits you because it boosts your borrowing power and gets away from the overly conservative calculation that Fannie Mae and Freddie Mac otherwise do on conventional mortgages. This is a win if you’re using an FHA loan to finance a primary home and you are carrying rental property.
The only other way to use rental income to qualify for an FHA loan is if you just acquire the other property and it is not time for you to file your tax return yet which point the lender will give you the benefit of using 75% of those rents that you have coming in to qualify to offset your mortgage payment. If you are coming up on tax time and you need that income to qualify, but you haven’t taken out a mortgage yet or are still house hunting it might be a prudent move to file an extension on your tax returns, so the lender is required to use 75% of your rents to qualify in that type of situation.
In some cases, it now may even make for sense for you to use an FHA Loan to finance a primary home vs a conventional mortgage just due to this rental income qualification change.
Having a tough time getting a mortgage? Get a no cost quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Does a Cash-Out Refinance Make Sense to Consolidate Debt?
A cash-out refinance can simplify high-interest debt, but it also turns unsecured balances into debt secured by your home. Here is how to decide if the math and the risk make sense.
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
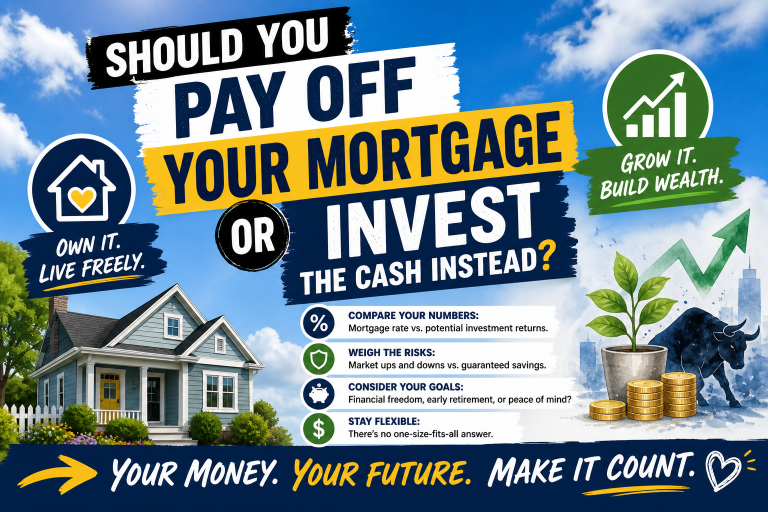
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!