
With the proliferation of new home buying programs being introduced into the market consumers today have more choices for securing financing than ever before. Here is how to pick what mortgage loan program for your unique financial profile…
Know this-take peoples thoughts and opinions with a grain of salt. Before you start looking at loan programs keep your business to yourself. If you happen to share your mortgage plan with anyone including friends and family, everyone will have an opinion of what you should or should not do with your loan. Unless these people are making a mortgage payment for you, take their opinions in stride. While this might sound harsh, the reality is that these people have no financial responsibility for the obligation you’re about to consider taking on. That said following are some financial profiles and recommended loan programs to help you choose what program is most suitable for you and your family.
If you have stable income, great credit, down payment and little to no debt
Then a conventional loan is likely your best bet
If you have stable income, great credit and no down payment and little to no debt
Then a conventional or FHA loan with down payment assistance could be your best bet or a USDA 100% financing loan.
If you have stable income, great credit, high monthly liabilities and no down payment
Then an FHA loan is probably going to be your best bet with down payment assistance
If you have stable income bad credit, high monthly liabilities and no down payment
Then an FHA loan would be the most suitable if your credit score is 640 or higher. If not going with a traditional FHA loan with gifted funds for a down payment would be optimal.
If you have a previous derogatory credit event in your past under the most recent last seven years
Then and FHA, VA or USDA loan would make the most financial sense as conventional loans or have a seven-year window on foreclosures and four year waiting window on chapter 7 bankruptcies.
Alternatively, your situation might not be described above. Perhaps it might mean having to get a cosigner, paying off debt or putting less money down on a home to pay off some liabilities improve your borrowing power.
97% all residential loans in the market today are government backed loans or government insured loans.Hopefully based on the information that you’ve learned you can now start to get a read on what mortgage loan program would be most suitable for you and your family so you can decide if that mortgage loan you’re looking up makes financial sense.
Looking to get a mortgage? Get a free quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
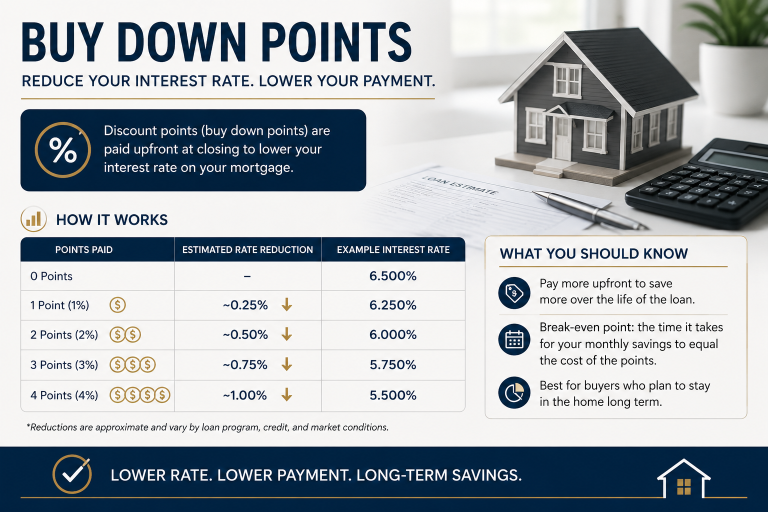
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.

blog idea
Does to make sense to cash refinance to consolidate debt? How to use child support…
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!