
If you were planning to buy a home or refinance one you already own, expect a lot of paperwork. Here’s one thing you probably didn’t know – tax returns are not required all the time.
Are you self-employed or W-2?
If you are a W-2 wage earner there is lower likelihood for needing to provide tax returns than there is if you’re self-employed. If you’re self-employed the only way a lender can determine what your income is to examine your tax returns. Your tax returns as a self-employed individual show how much money you earned versus netted. There are some situations where you can get away with using one income years of tax returns, such as changing from being W-2 to self-employed.
Automated underwriting findings
Mortgage lenders ask for two years of tax returns, two years of W-2s and pay stubs for the most recent last 30 days. Every mortgage in America sold on the secondary market is ran through automated underwriting. If you are a W2 wage earner and the automated underwriting findings do not require tax returns, you may not need to provide returns at all in order to qualify close on a home.
To be clear we are talking about a straight W-2 wage earner. Any of the following things could trigger needing the full two years of tax returns despite being an employee.
- Rental income
- Social Security income
- Pension income
- Schedule C income beyond your normal W-2 job
- Partnership in a business or another entity
Some banks have additional requirements
When you apply for a loan it’s generally a good idea to provide the two years of tax returns, two years of W-2s and the 30 day pay stubs all lenders ask for. However there is a saying in mortgage lending, provide “what is needed.” Providing only what is asked for can go a long way in your approval as there is less documentation to be scrutinized.
If automated underwriting dictates what documentation you must provide to obtain financing. Some banks have additional requirements, that even if your loan does not require the need to provide tax returns, their individual banking policies do require that you provide tax returns. Such requirements are due to that bank’s relationship with Fannie Mae and Freddie Mac or that particular company’s appetite for risk.
A good rule of thumb is to provide the bare bones minimum requirements clearly and concisely, so there is no questions about your ability to qualify. When your loan is reviewed conditions come into play. These conditions should be interpreted as “give us more information and your loan is clear.” These conditions are normal component to loan underwriting and proving tax returns may not be an problematic so long as specifically not needed by automated underwriting.
The key is to work with a lender who has a makes sense approach to financing, rather than one who promises ultra low rates, but is so risk adverse your loan never ends up closing escrow.
Looking for a mortgage? Get a quote online now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
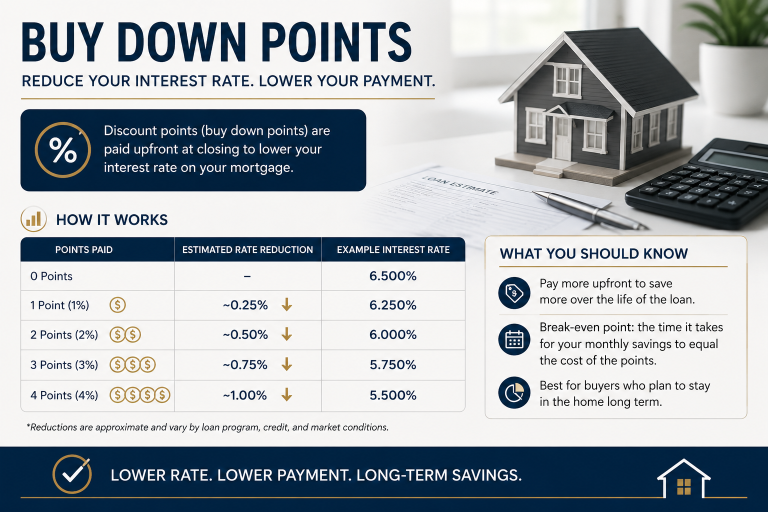
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
Income, Credit, and Down Payment: How Mortgage Approval Really Works
Mortgage approval is about more than a credit score. Learn how income, debt, credit, and down payment work together when buying a home.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!