
HUD recently announced the FHA Loan Limits for 2019 have been increased. This increase includes VA loan limits for both refinancing and home buying.
These changes will represent more opportunity for families to finance bigger mortgages going forward as the limits across the country have increased. Even the low-cost areas which represents 65% of the conforming loan limits set at $484,380 have increased up to just over $314k.
For example, in Sonoma County California the loan limit was increased to $704,950. This means you can now purchase a house in Sonoma County California with 3.5% down for a single-family residence and get an insurable 30-year fixed rate mortgage up to $704,950.
This also means you can refinance a first mortgage and a second mortgage as a rate and term refinance doing the first and second combination into one new loan and the loan can still be considered a rate and term refinance. This can be particularly valuable for someone who has a first mortgage and a home equity line of credit that is an adjustable rate that they are now combining into one new loan. FHA loans can be finance up to 96.5% loan to value. Families buying homes that don’t have a big down payment but have strong income and sufficient credit can also now enter the market and be able to play ball at a higher loan amount to help in a competitive purchase offer situation.
Both FHA Loans Limits and VA Loans in community property states require the lender pull the credit of the spouse and their debt is counted against the payment to income ratio for the mortgage. One caveat to this is that the VA will soon be announcing that income from the spouse whose debt is being counted in a community property may be offset with their incomes subsequently not adversely affecting the primary borrower’s borrowing power.
These FHA changes all represent a borrower being eligible for a mortgage after the following negative derogatory credit situations:
- 3 years after a foreclosure
- 3 years after a short sale
- 2 years after a Chapter 7 bankruptcy
- 1 year after a Chapter 13 Bankruptcy
One thing however about the FHA that holds does is that you are unable to refinance an FHA loan for a borrower into a new FHA loan who has not owned and lived property and lives in the property for the most recent last 12 months. If you’re looking for an FHA Loan or need some mortgage guidance reach out today for a complimentary cost quote.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
What to Know About Getting a Mortgage Loan in a Community Property State With FHA or VA Financing
In a community property state such as California, a non-borrowing spouse’s debts can still affect FHA or VA mortgage qualification. Here is what buyers need to know.
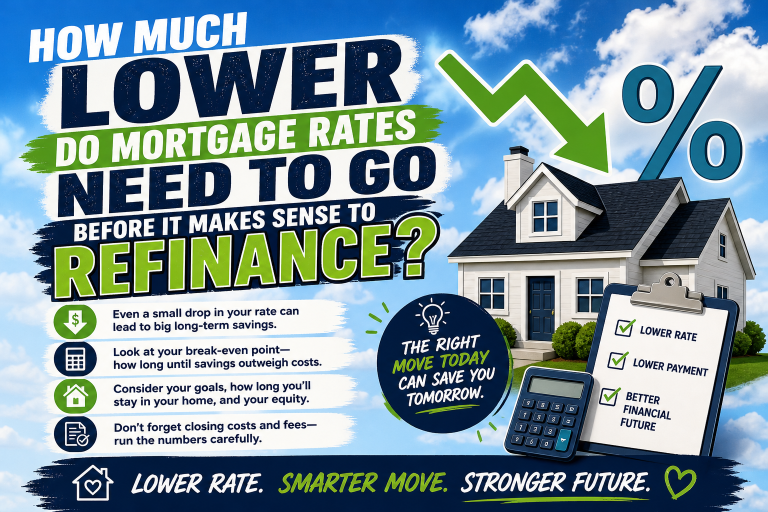
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!