
Traditionally, self-employed mortgage borrowers are more heavily scrutinized by mortgage companies because of their gyrating income. If their business stops the revenue stops and their ability to make a mortgage payment could be impacted. That’s the rationale behind why lenders look at self-employed borrowers more stringently.
Lenders request both personal and or corporate returns from self-employed borrowers. Lenders generally must average these returns out over a two-year period. Not a bad thing if you’re showing enough income, but absolutely could be problematic if one year was strong and another year was bad.
Nontraditional way of securing mortgage financing is to use alternative forms of income documentation especially if your tax returns don’t paint a favorable picture.
One such method is to use a bank statement program. Know this- bank statement programs vary from lender to lender. The more relaxed from a guideline standpoint, the pricey your mortgage will be. Your biggest goal when getting alternative form of qualifying should not be rate and cost, but it should be payment and ability to qualify-that should be your focus. It goes without saying that you’re going to pay more for such type of financing then if you supplied traditional supporting documentation in the form of federal tax returns.
Some characteristics of bank statement loans;
- At least a mi- 680-credit score with no previous derogatory credit any kind that means no bankruptcy, no short sale and no foreclosure.
- You’ll need at least 25% down or a 25% Equity position in the house if you’re refinancing.
- Up to a 50% debt to income ratio can be considered
As previously mentioned the rate and the pricing associate with such a program is going to be more than if you were going with traditional financing so for example traditional financing for 30-year fixed rate mortgages with excellent credit and super strong equity in the property for a single-family home is hovering just a hair under 4% now.
This would mean that for a non-traditional program it’s realistic that you be paying to the mid 4’s or a low 5’s range possibly even paying one discount point associated with your mortgage.
If you’re looking to do this when you pick a lender, provide them everything they ask for that includes letting them pull a copy of your credit report and run their ratios, run their calculations and provide them all the supporting financial documentation they request. Not half of the information, not part of the information – you must be willing to just accept that when you have a unique financial situation you must be willing to provide them all your supporting documentation, so they can pragmatically tell you how they can help you be successful on your purchase or refinance.
Looking for a non-traditional loan? Get a no cost quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
What to Know About Getting a Mortgage Loan in a Community Property State With FHA or VA Financing
In a community property state such as California, a non-borrowing spouse’s debts can still affect FHA or VA mortgage qualification. Here is what buyers need to know.
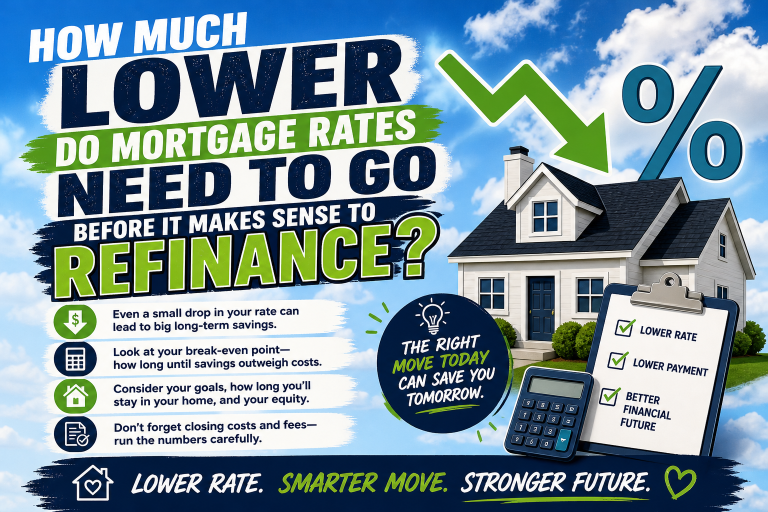
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
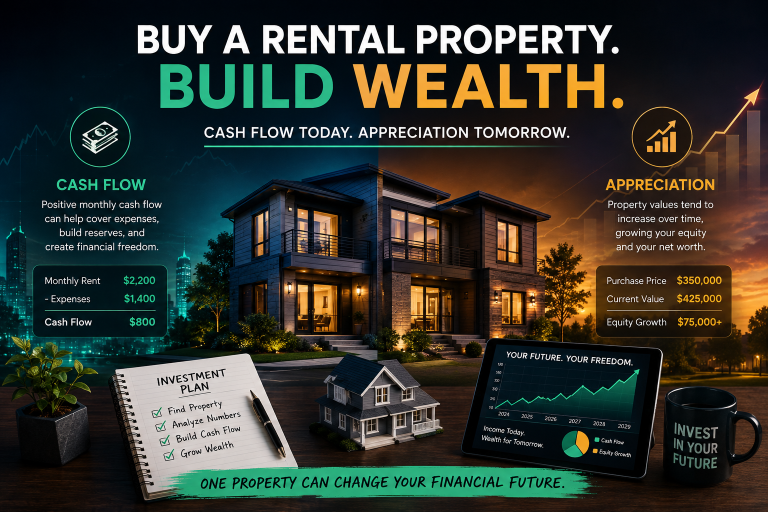
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!