
Refinancing Strategies to Reduce Credit Card Debt and Buy a Home
If you’re sitting on a 3% mortgage and juggling high-interest credit card or auto loan debt, you’re not alone. As of early 2025, the average American household carries about $7,321 in credit card debt, with interest rates often exceeding 20% . This financial strain can hinder your ability to save for a home or manage monthly expenses.
Option 1: Consolidate with a New First Mortgage
One approach is to refinance your existing mortgage, combining it with your high-interest debts into a new loan. While this can simplify payments and potentially lower your overall interest rate, it also means relinquishing your current 3% mortgage rate. Moreover, extending your mortgage term could result in paying more interest over time.
Option 2: Secure a Fixed-Rate Second Mortgage
Alternatively, consider taking out a fixed-rate second mortgage to specifically address your high-interest debts. This strategy allows you to maintain your favorable first mortgage rate while tackling credit card or auto loan balances.
-
Lower Monthly Payments: Second mortgages often have lower interest rates than credit cards, reducing your monthly obligations.
-
Improved Credit Score: Paying off high-interest debts can decrease your credit utilization ratio, positively impacting your credit score.
-
Financial Flexibility: With reduced debt payments, you can allocate more funds toward savings or other financial goals.
Considerations Before Refinancing
Before proceeding, assess the following:
-
Home Equity: Ensure you have sufficient equity in your home to qualify for a second mortgage.
-
Loan Terms: Understand the terms of the second mortgage, including interest rates and repayment schedules.
-
Financial Discipline: Commit to responsible spending to avoid accumulating new high-interest debts.
Conclusion
Refinancing through a second mortgage can be a strategic move to manage high-interest debts while preserving your low-rate first mortgage. By carefully evaluating your financial situation and consulting with a mortgage advisor, you can make informed decisions that align with your homeownership aspirations.
Looking to get a mortgage get a free rate quote right now.
Share:
Posted in: buying a home, credit card debt, credit score improvement, credit utilization, debt consolidation, financial planning, fixed-rate second mortgage, home equity, homeownership, homeownership goals, managing debt, mortgage advice, mortgage refinance, mortgage tips, personal finance, refinance strategies, refinance vs second mortgage, refinancing strategies, second mortgage
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
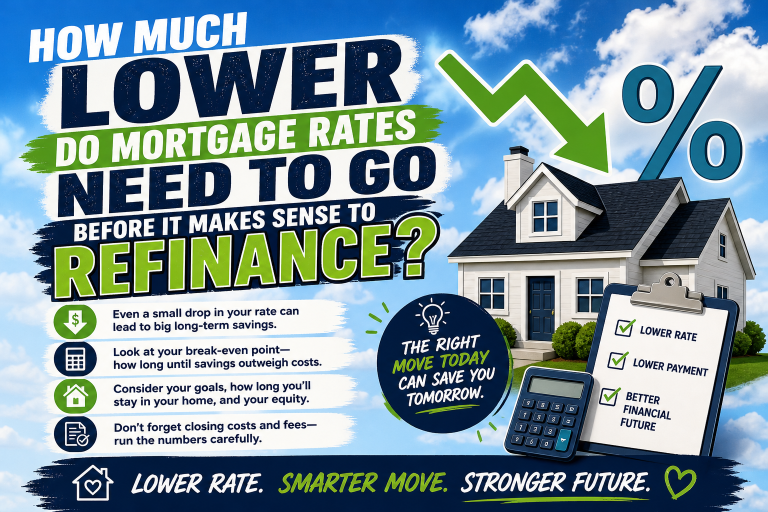
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
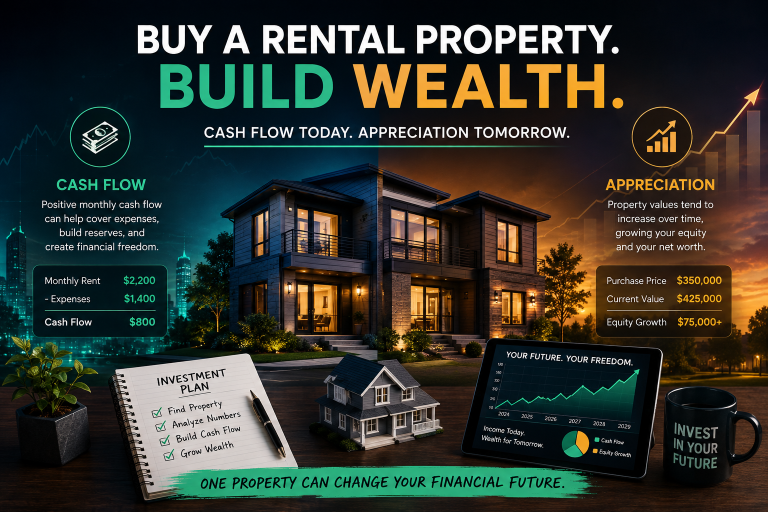
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
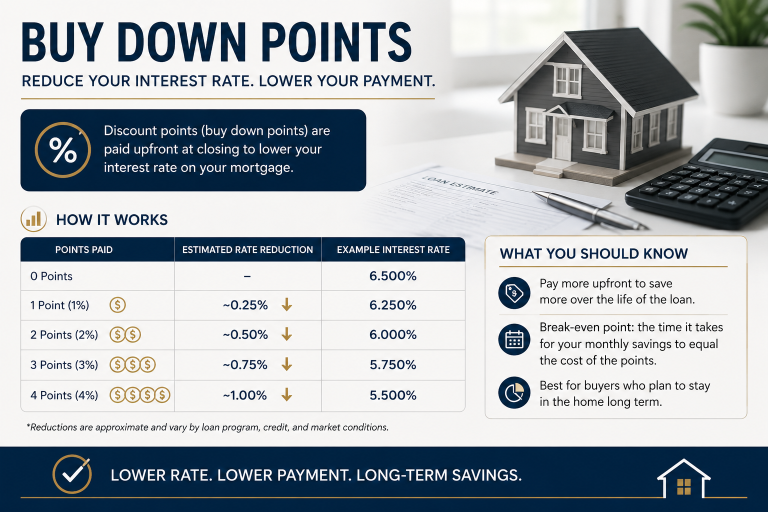
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.

blog idea
Does to make sense to cash refinance to consolidate debt? How to use child support…
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!