
If you’ve got solid credit and a decent amount of cash on hand—but no W2 income or traditional job—you might be wondering if it’s still possible to buy a home. The good news? It is, thanks to a lesser-known financing option called the Debt Service Coverage Ratio (DSCR) loan.
This mortgage product is designed with real estate investors in mind, but it’s increasingly being used by savvy buyers who want to live in the home, especially when other conventional loans are out of reach due to income documentation issues.
Let’s break down exactly how this works—and how you can leverage it to purchase a property.
What is a DSCR Loan?
DSCR stands for Debt Service Coverage Ratio. Unlike traditional mortgages that rely heavily on your job history and W2 income, DSCR loans focus on the property’s cash flow, not your personal income. This means your approval is largely based on how much rent the property can generate compared to the proposed monthly mortgage payment.
This is a game-changer for:
-
Self-employed individuals
-
Retirees with investment assets
-
Entrepreneurs between ventures
-
People with recent job changes or non-traditional income
The Basic Math Behind DSCR Loans
The key metric is the DSCR ratio, which compares monthly rental income to monthly housing expenses (including principal, interest, taxes, insurance, and HOA if applicable).
-
DSCR = Rental Income / PITIA (Mortgage Payment)
For example, if a property brings in $3,000 in monthly rent and your total mortgage payment is $2,700, the DSCR would be 1.11. That’s often enough to qualify.
Some lenders require a DSCR of 1.0 or higher, meaning the rent covers at least 100% of the payment. Others are more flexible and allow for ratios as low as 0.75, especially if you’re putting more money down or have reserves.
How Much Do You Need to Put Down?
Most DSCR loans require a minimum of 20% down, though some may accept as little as 15% for strong borrowers. That said, the more you put down, the better your terms typically become.
A 20% down payment helps you:
-
Avoid mortgage insurance
-
Get a more favorable rate
-
Offset a lower DSCR if needed
-
Show skin in the game, which lenders love
Can You Move Into the Property?
Technically, DSCR loans are for non-owner-occupied properties—but many buyers use this strategy to initially purchase the home as an investment, then move in later. Some even convert the garage or a portion of the home into a rentable unit, helping it cash flow from day one.
Speak with a knowledgeable mortgage advisor to ensure this move-in plan is structured properly and within guidelines.
What Do You Need to Qualify?
-
Good credit score (typically 680+)
-
20%+ down payment
-
Proof of rent (appraisal with rental schedule or existing lease)
-
Cash reserves (some lenders require 3–6 months of payments)
Final Thoughts
If you’re sitting on cash, have great credit, and are tired of being told “no” because you lack traditional income, a DSCR loan could be your golden ticket to owning real estate.
It’s an elegant workaround for those who want to invest—or even move into—a property without a job or W2 wages.
Looking to get a mortgage? Get a no cost rate quote today!
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
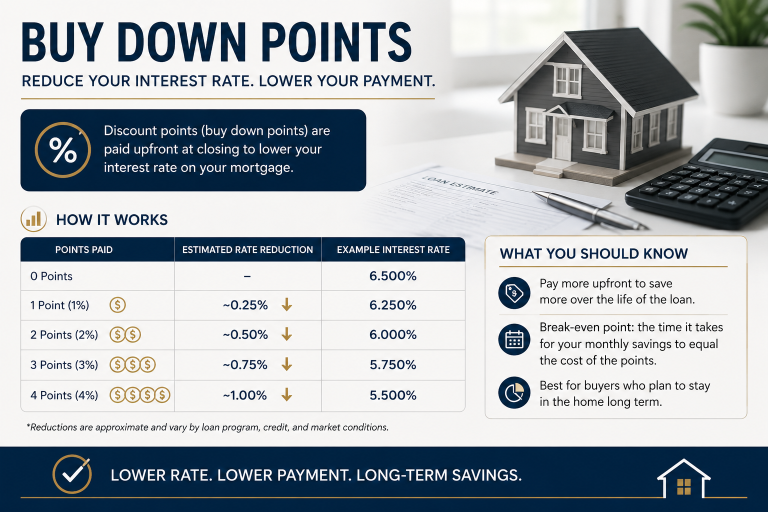
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!