
When you refinance your mortgage, someone is on the hook for paying fees. Who Following are the only ways loan fees can be accounted for when refinancing….
When you refinance your home closing costs are an inevitable component that must be paid for the transaction to successfully fund and close escrow. Here are the two bar none ways fees are accounted for; Lender paid where the lender pays the closing costs associated with your mortgage based on the interest rate you choose.
For example, let’s say you are being quoted a 30-year fixed rate at 3.875% at no points and you were comparing that to a rate of 4.25% with a lender credit at $3k. The lender credit for $3000 at 4.25% interest rate would cover the closing costs associated with your loan. This is called a no points no fees loan. It is also sometimes referred to as a no-cost refinance. Borrower paid-Borrower paid closing costs means these monies are rolled into the loan amount or paid for with cash due at closing.
For example, if you owe $300,000 on your house and you’re rolling your closing costs into your mortgage your new financed loan amount would be $303,000. The other way with borrower paid closing cost is bringing the monies due to closing. Do not be fooled if you’re rolling your closing costs into your mortgage that is not a no-cost mortgage.
Some lenders might try to convince you otherwise, but that is not accurate. Any closing cost you are rolling into your loan means that you are paying fees associated with your refinancing your mortgage. No cost loans only work with you taking a rate above market to generate an overage to pay the closing costs associated with your loan. Alternatively, gift money is always a possibility on a primary refinance residence transaction.
Such a scenario would fall into the category of being borrower paid since it’s being paid for on behalf of the borrower by another party. When you are comparing mortgage offers make sure when you were going over the terms with your lender you specifically know what party is paying what fee so you can decide the most makes sense option for you.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
What to Know About Getting a Mortgage Loan in a Community Property State With FHA or VA Financing
In a community property state such as California, a non-borrowing spouse’s debts can still affect FHA or VA mortgage qualification. Here is what buyers need to know.
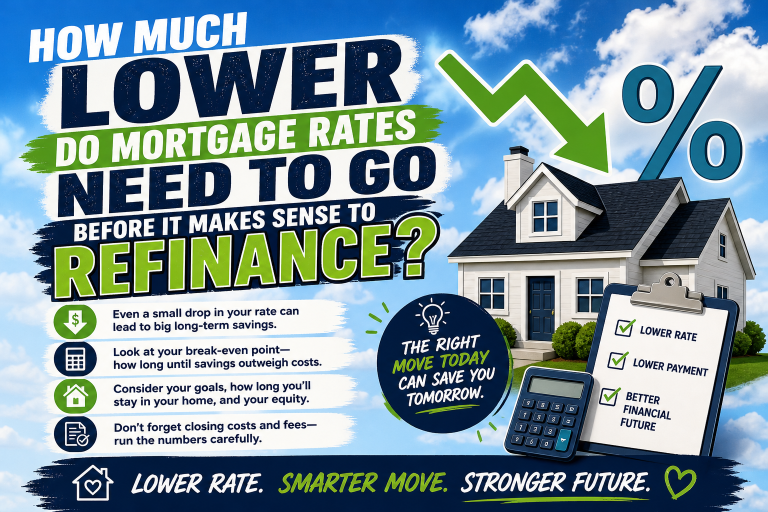
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
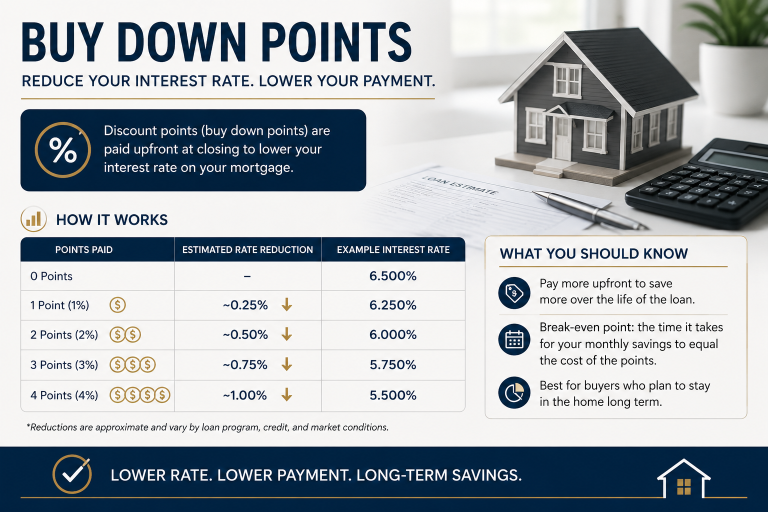
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!