
If you are like most consumers, you want to have a clear understanding of the fees associated with a mortgage. The closing process, lender fees, title fees, etc. This is so you know exactly how all the numbers add up. Here is something you need to know regarding getting title insurance when purchasing or refinancing your home.
When you take out a mortgage loan, you will see in the disclosures, you will receive these from your lender, title insurance is something you can opt out of. While this is technically true, no lender will fund your loan without title insurance in place.
Title insurance is to make sure the house you are purchasing is free from any other liens, encumbrances or any other parties that may have legal interest in the property. When you purchase a home for the first time, there are two forms of title insurance you are obligated to purchase. The first is a Lender’s Policy, which protects the lender against other interested parties. The second is an Owner’s Policy, which protects you. Any transactions you do on your property in the future, such as Subsequent Refinancing, would require you to purchase a Lender’s Policy.
Within the loan disclosures you receive, as an informed consumer, there is verbiage that says you can opt out of title insurance. You can do this if you are not using financing to purchase the property. No lender would be granting you a mortgage to purchase a property without title insurance in place. This is because it protects them as well as making sure they are repaid the money they are lending you.
Picture this: You purchase a home with mortgage loan financing. The transaction closed and down the line another party comes along with the Grant Deed, showing they should rightfully be on title. In such a scenario, the lender would have exposure for getting repaid. Especially if the other party was awarded the property, because there was no protection from the start.
Title insurance is expensive. As discussed above, purchasing a home requires two forms of title insurance. Refinancing only requires a Lender’s Policy as you are only required to purchase an Owner’s Policy when you purchase the home. Each time you refinance, there is a new title insurance policy. This is typically built into the closing cost the lender gives you in the form of a Non-Reoccurring Closing Cost, meaning a one-time expense.
Know when you purchase a home for the first time, you are going to be required to purchase a title insurance policy.
Looking to purchase a home? Get started by getting a free mortgage rate quote online today.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
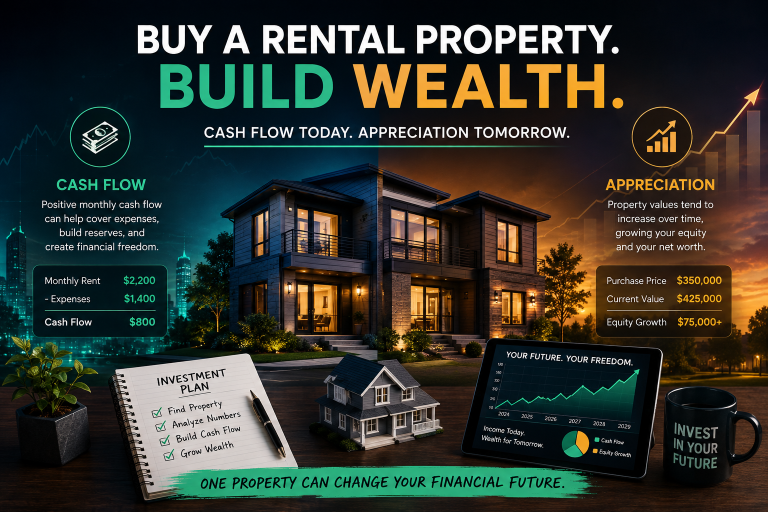
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
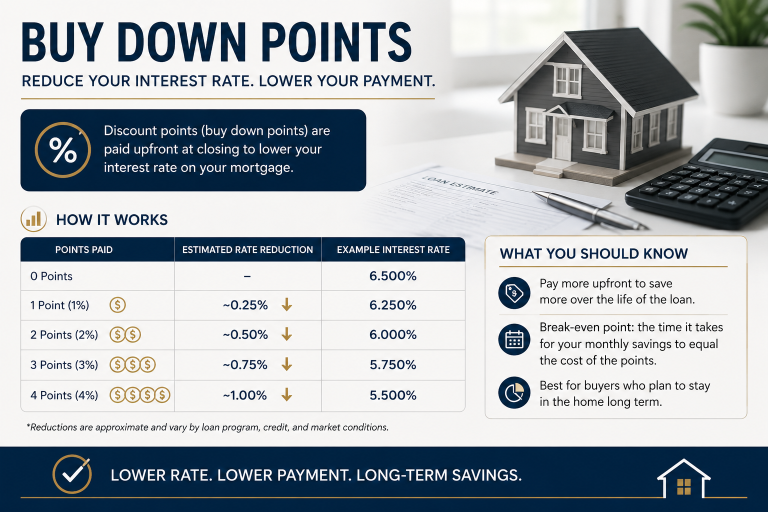
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!