
Been turned down for a mortgage recently? Fear not, this recent change to conventional mortgages just made your chances of qualifying easier. Here is the latest …
Fannie Mae recently changed their policy regarding restructured loans virtually eliminating many roadblocks. Fannie Mae had extra credit requirements in place for borrowers who had restructured mortgages in the last several years. A restructured mortgage is a mortgage loan that had some material change to the loan amount, rate or payment or term benefiting the borrower due to some sort of financial hardship or material change from the original terms. Examples includes an adjustable rate mortgage being converted to fixed rate mortgage or payment term was stretched from 360 months to 480.
Here is what this means to consumers. If you had a mortgage that was modified in the last 12 months in order to qualify for a new conventional mortgage loan, you would have needed minimum of 24 months payments paid as agreed when financing that property or 12 months from the date of the original loan restructuring if you were trying to finance another property. These credit requirements took precedence over down payment, debt to income ratio and yes even credit score. These terms were put in place by Fannie Mae back in 2008 when the secondary mortgage market was unsure of how these loans would perform overtime.
If you had a restructured loan in your past you will not be precluded from qualifying anymore. These changes are for conventional mortgage loans only. Most other programs including the FHA and Jumbo mortgages mirror conventional underwriting and will soon likely follow suit and change their policies on restructured mortgages as well.
Currently, there is a combination of two things working in your favor to reapply for mortgage loan financing… super low interest rates brought on by Brexit and an opportunity to get out of the short-term restructured the loan from years past. If you no longer have a restructure the loan in your name, you need not worry, as the limiting policy is now a thing of the past.
As with any home loan you’ll still need to be able to show a healthy credit score, stable income, a low debt income ratio and of course equity. You’ll need to be able to pass the cash income credit test when applying for a home mortgage.
Looking to get a mortgage?
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
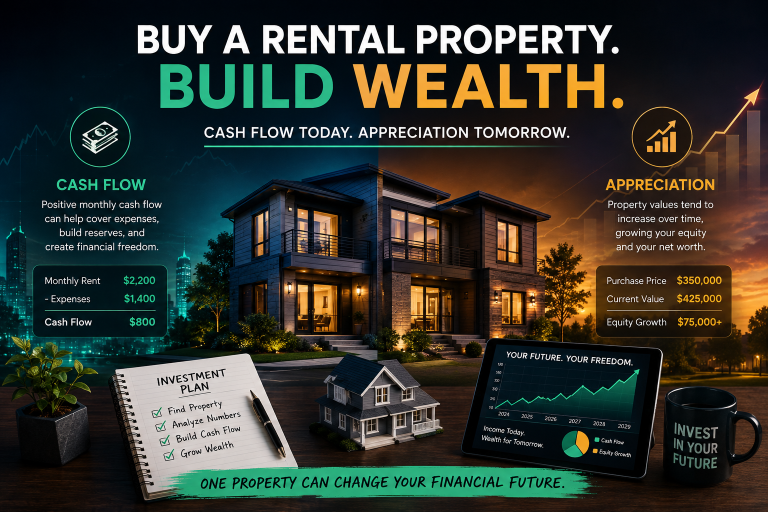
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
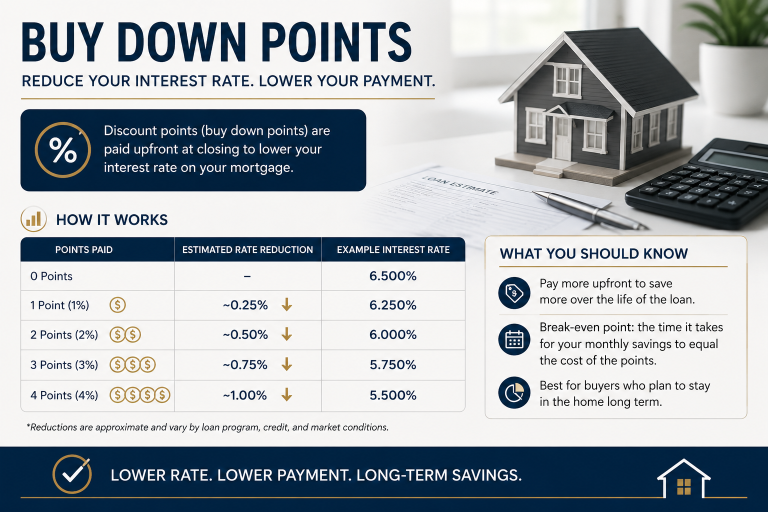
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!