
One of the challenges some families may have when seeking a mortgage is not showing enough income on paper via tax returns to qualify. Here’s some nuances about bank statement programs that might help you land a mortgage more successfully…
Traditionally when getting a mortgage most mortgage companies are going to want your W-2s or your pay stubs for supporting income to get a mortgage. If you’re self-employed there you will usually want your tax returns. In most cases the problematic element of tax returns that makes getting a mortgage more difficult is that most mortgage companies want to blend two years of tax return income together. That means if you had a good year and a bad year the bad year will adversely affect your income in the income averaging.
There is a program that in some cases will allow you to get a mortgage filing self-employed for last five years wherein the lender uses the most recent year of income tax returns to qualify. That might help some families, but it’s still predicated on using your tax returns. Some mortgage offer bank statement programs, one such lender SecurityNational Mortgage Company offers such a program. The program is truly a bank statement for income documentation loan. Here’s some nuances about the program that might help you land a mortgage more easily
- 1 year or 6 months of bank statements needed for supporting income
- Program allows for getting a mortgage 2 years after a short sale bankruptcy or foreclosure
- Loans to $1,000,000 and in some cases to $2,000,000
- Minimum credit score 680
- Up to a 50% debt to income ratio
- 25% equity minimum
Program can be used for a primary home, second home and for a rental property and allows for in some cashing out.
If you’ve been turned away for a mortgage because you have a complex financial profile this program could be a very flexible gap between bridging where you are financially right now and where you otherwise could be. Most traditional mortgages 30-year fixed rate loan supports rates presently in the low 4’s This program supports rates in the high 4’s/.
If you’re desiring to purchase or refinance a house and have been turned away before you owe it to yourself to at least explore the possibility of a bank statement program. The program is incredibly flexible and allows for out-of-the-box scenarios whereas most mortgage companies will turn in the towel the key is at work with a lender who is willing and able to explore your loan no matter how unique challenging or complex it otherwise might be.
Looking to get a mortgage? Get a no cost quote now.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
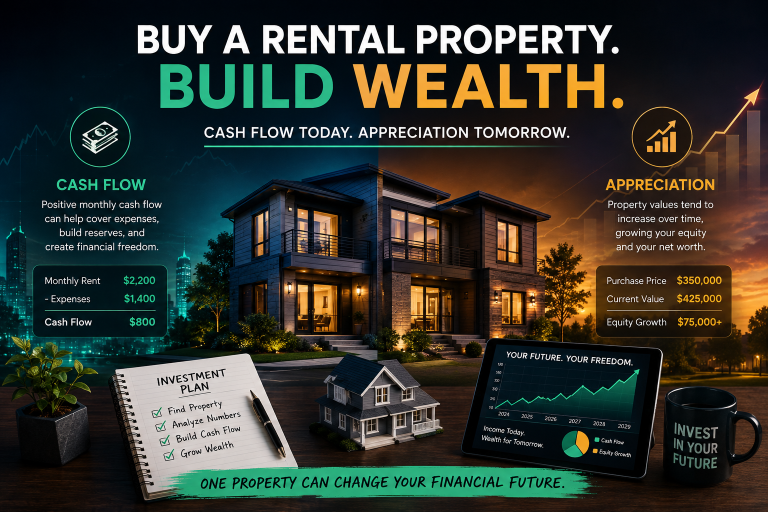
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
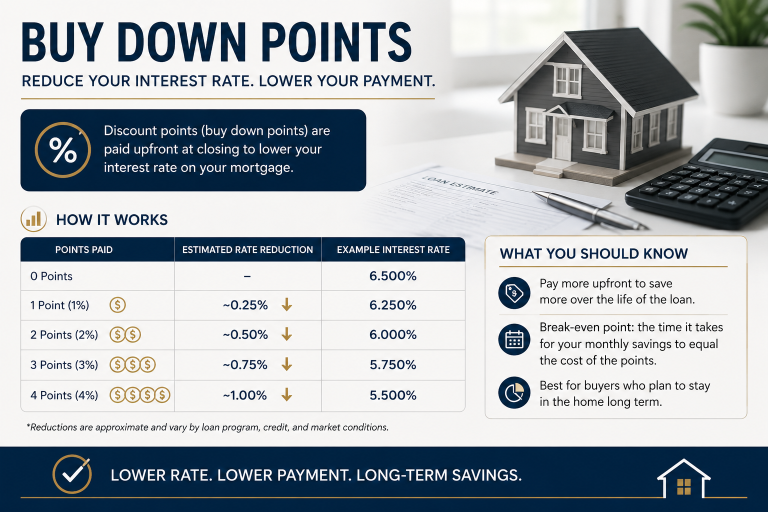
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!