
Discount point are nothing more than upfront head you pay to purchase a lower interest rate and subsequently a lower monthly payment. In some case the you may not have a choice to pay discount points. Following are those ways…
It is reasonable to assume when refinancing with a lower than 660 credit score on a conventional mortgage loan and pulling cash out of a primary residence, second home or rental property will automatically mean you paying some form of a discount. No matter what interest rate you are looking at. This is a byproduct of a market that prices and hedges pricing commensurate with the cost of risk a lower credit score borrower poses.
This also means for example on an FHA mortgage and you’re doing a cash out refinancing with credit scores 580-619 you are going to be paying some amount of money in a discount point. It is not unreasonable with a credit score under 600 you may be paying as much as 1-2 discount points of your desired loan amount.
The factors that cause the discount points to come in the play is:
- Loan to value more than 70% with credit scores under 700 on conventional loans
- Cash out refinances greater than 70% loan to value on conventional
- Must have goal of specific rate
- Investment property mortgages
- FHA Mortgages purchasing or refinancing with scores 619 or lower
- A must have interest rate on an FHA Mortgage
Talk to your lender when you’re being quoted points. Most lenders have options to toggle between so you can see the cost-benefit for a rate. The points system works by a sliding scale. The lower the interest rate, the more cost in the form of points there will be associated with that interest-rate. The higher the interest rate the less the costs are however the more expensive the loan is over the longer-term because the interest rate is higher you subsequently pay more interest of all over the total term of the loan. A sound mortgage loan scenario would be to estimate rate and cost vs how long you will need to borrow the money for. For example, you wouldn’t want to take a loan with extra fees if you plan to sell the home before you recoup those monies anyway.
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
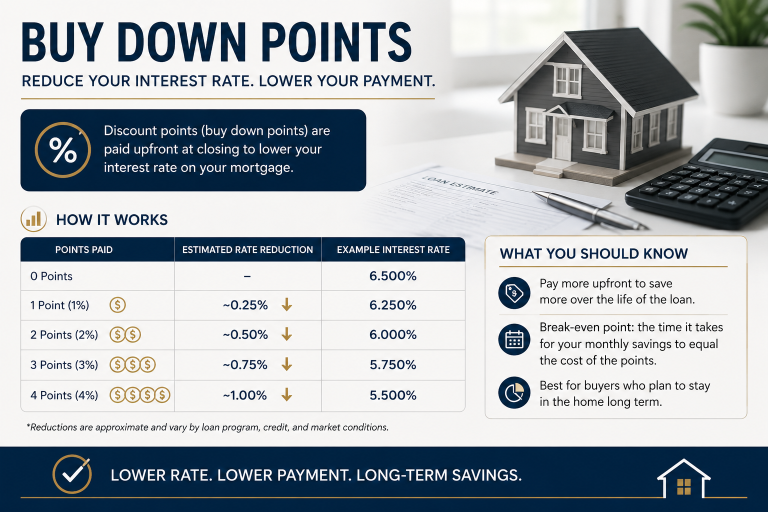
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.

blog idea
Does to make sense to cash refinance to consolidate debt? How to use child support…
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!