
Tight lending guidelines, restrictive loan qualifying, and lack of available credit continues to dominate today’s world of mortgage lending. Despite the fact consumers need to show full income, all liabilities, explain previous job history, credit challenges and the list goes on, what many don’t realize, is there something else more ominous lenders’ have their feelers out for that exists in every home loan application.
Acceptable funds for the transaction
- Whose funds are being used?
- Where did the money originate from?
Bank Statements Only Share Half The Story
Bank statements show the available funds for use in the transaction, but are these funds legitimate?
*Lenders will be especially keen on inconsistent and random cash deposits going into a bank account. Simple as this may sound, this causes more problems and challenges for consumers trying to secure mortgages today, than the debt to income ratio or any other credit characteristic.
If: any bank statement deposit is more than 25% of your income
Then: monies will have to be sourced with a clear letter of explanation, potential gift letter if the money came in the form of a gift, along with a bank statement from the person gifting that money showing they had the ability to do so
If: any deposits are less than 25% of your income
Then: these funds can be used in the transaction although consumer may be asked to explain where the funds came from, however, no sourcing/paper trailing will be needed
If: cash is from side job/side work
Then: if needed for the transaction, money will have to be “seasoned” for a period of 60 days, meaning those funds are ineligible for use in the loan transaction until two statement cycles have surpassed thus making those funds eligible
If: deposit is gift money
Then: the person giving the gift needs to show on paper a clear ability for them to gift money to the recipient, in other words, a friend of the person giving the gift can’t make a deposit in giftor’s account without getting a clear and concise explanation including a gift letter and subsequent paper trail with bank statements showing where funds originated and where funds ended up.
If: additional reserves are needed, i.e. two months of mortgage payments liquid in the bank (typically needed)
Then: consumer must meet 60 day seasoning requirement, unless funds are from paychecks in the normal course of pay periods.
What This Consumer Mortgage Mistake Costs
Should any one of the above referenced scenarios take place, plan on a longer close of escrow and a subsequent longer interest rate lock. The longer a transaction takes, the higher the cost. Circumstances like gathering together financial documentation last minute, sourcing monies and/or getting contractual purchase contract extensions which often run as high as $100 per day for every day the transaction does not close on time, are all examples how important timing is.
It is ideally in the best interest of the consumer to handle the paper trailing concerns and credit characteristics with the lender upfront, so it doesn’t become an issue later on when loan contingencies need to be removed or when the refinance slated to close is delayed because an updated statement shows deposits inconsistent with the borrower’s income. Contact ScottS@snmc.com for your next mortgage!
Share:
Posted in:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
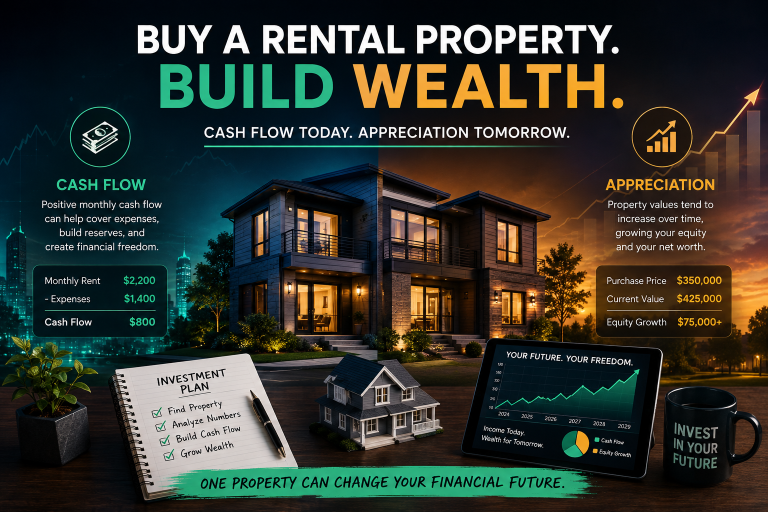
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
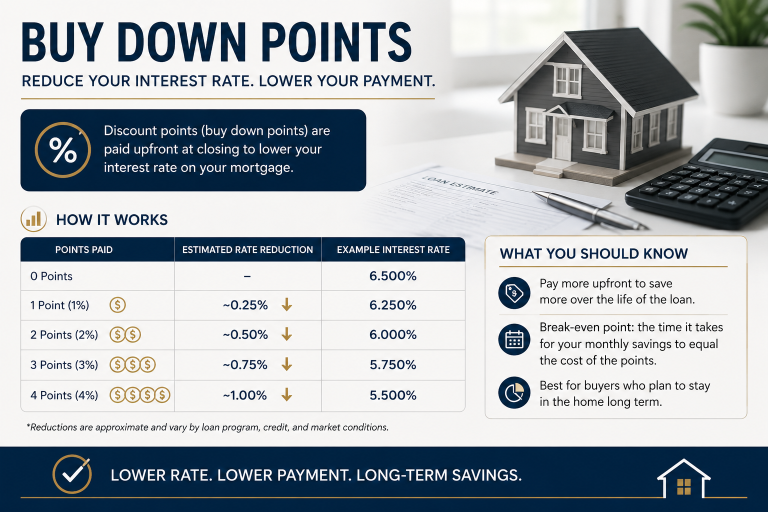
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
Income, Credit, and Down Payment: How Mortgage Approval Really Works
Mortgage approval is about more than a credit score. Learn how income, debt, credit, and down payment work together when buying a home.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!