
Buying a rental property can feel like a big fork in the road. One home may produce more monthly income today, while another may be in an area with stronger potential for future price growth. Neither goal is wrong. The better choice depends on what you need the property to do for you and how long you can afford to hold it.
Cash flow and appreciation often work together over time, but they are not the same thing. Cash flow helps a rental support itself now. Appreciation can build wealth on paper and create options later. A solid investment plan looks at both, along with the risks that come with owning a rental.
Cash flow is about what the property does each month
Cash flow is the money left after the rent pays the property’s regular costs. Those costs include the mortgage payment, property taxes, insurance, repairs, maintenance, vacancy periods, and property management if you use it. Positive cash flow means income is greater than expenses. Negative cash flow means you are adding money from your own pocket.
For many investors, cash flow provides breathing room. A rental that covers its costs is easier to hold through changes in the market. It can also create income that may help with future repairs, savings goals, or retirement planning.
Let’s say a rental collects $3,500 per month in rent. The mortgage, taxes, insurance, and management total $2,700. You set aside another $400 for repairs, maintenance, and vacancies. That leaves about $400 per month in cash flow before income taxes. It is not a huge windfall, but it gives the property a cushion.
The mistake is looking only at rent minus the mortgage payment. Every property will eventually need repairs. Tenants move out. Insurance and taxes can rise. A smart cash-flow estimate includes realistic reserves, not just the best-case month.
Why cash flow matters for long-term ownership
Positive cash flow does not guarantee a good investment. However, it can make it easier to stay patient. If the market slows or values dip for a period, the property may still be paying its way. That matters because real estate often rewards owners who can hold on through normal market cycles.
Cash flow can also help you qualify for future financing, depending on the loan program and the documented rental income. Lenders still review your credit, income, assets, debts, and the property itself. Rental income is helpful, but it is not treated as automatic spendable income in every situation.
Appreciation is about future value and growing equity
Appreciation means the property rises in value over time. In Sonoma County and other high-cost California markets, investors often pay close attention to this. A property in a desirable location may have modest cash flow at first, yet gain value over a long holding period.
Here’s the thing: appreciation is never guaranteed. Local jobs, housing supply, interest rates, insurance costs, property condition, and buyer demand all affect value. A property can appreciate over many years and still have flat or declining periods along the way.
Let’s say you buy a rental for $700,000 with a $140,000 down payment and a $560,000 fixed-rate mortgage. After several years, the property is worth $825,000. At the same time, regular mortgage payments have reduced the loan balance to $520,000. You now have roughly $305,000 in equity before selling costs or any new loan costs.
That equity came from two places. Part came from appreciation, or the increase in market value. Part came from paying down the principal balance. This is one reason a fixed-rate mortgage can be useful for a long-term rental strategy. The principal-and-interest payment stays the same, while the loan balance gradually declines with each scheduled payment.
Of course, fixed payments do not mean all ownership costs stay fixed. Taxes, insurance, maintenance, and association dues can change. Rent may also change. Investors need to look at the full picture rather than assuming a fixed-rate loan makes a rental predictable in every way.
The best rental plans usually consider both goals
Cash flow and appreciation are not opposing teams. A property with strong cash flow today may also appreciate. A property purchased partly for appreciation may become a better cash-flow property later as rents rise and the mortgage principal is paid down.
The question is really which factor needs to carry more weight at the beginning. If you need the rental to provide income soon, cash flow deserves a hard look. If you have stable income, a long timeline, and can handle leaner early years, appreciation may matter more.
Before making an offer, run a conservative plan. Include the actual expected rent, not just the highest rent you hope to collect. Budget for turnover, repairs, and larger future items like roofing or appliances. Ask yourself whether you could keep the property if rent fell or an unexpected expense showed up.
It also helps to be honest about your time horizon. Appreciation is generally a long-game strategy. Selling after a short period can expose you to transaction costs, market swings, and tax consequences. A rental that only works if everything goes perfectly is usually too tight.
For a closer look at how these two forces can work together, see how to build cash flow and equity. The goal is not to chase one number. It is to own a property that fits your actual financial life.
Using equity to buy another property
As a rental gains value and the mortgage is paid down, some owners choose to use their equity for another purchase. A cash-out refinance replaces the existing mortgage with a new, larger loan. The difference can be received in cash and used for a down payment on another investment property.
For example, if your rental is worth $825,000 and you owe $520,000, a lender may allow you to borrow a portion of that equity. The exact amount depends on the loan type, property type, credit, income, reserves, appraisal, and loan-to-value limits. Investment-property rules are often stricter than rules for a primary residence.
A cash-out refinance can help an investor keep the original property while accessing some equity. But the new loan comes with closing costs, a new interest rate, and a new payment. Pulling out too much can weaken the property’s cash flow. It also turns paper equity into real debt that must be repaid.
That is why the decision should not be based only on how much cash is available. The more important question is whether both properties can still handle their expenses with a realistic reserve. If you are weighing ways to access equity, this overview of cash-out refinancing versus borrowing from family explains some of the tradeoffs.
Tax benefits and 1031 exchanges, in plain English
Rental property owners may be able to deduct certain ordinary expenses related to operating the rental. Common examples include mortgage interest, property taxes, insurance, management fees, repairs, and some professional fees. Depreciation may also allow an owner to deduct part of the building’s cost over time. Land is not depreciable.
These deductions can reduce taxable rental income, but tax rules can get complicated quickly. Rental losses are often treated as passive losses, and limits may apply depending on your income and participation. A tax professional should review your personal return before you count on a tax benefit.
A cash-out refinance is generally not taxable income because it is borrowed money, not profit from a sale. Still, the interest and deductibility rules depend on how the borrowed funds are used. Keep clean records if refinance proceeds are used for an investment purchase or improvements.
If you decide to sell one investment property and buy another, a 1031 exchange may allow you to defer capital gains tax and depreciation recapture. It does not erase the tax. It generally moves the tax obligation into the replacement property.
To qualify, the exchange must follow strict rules. The properties must generally be held for investment or business use, not as a personal residence. You must use a qualified intermediary, identify potential replacement properties within 45 days, and complete the purchase within 180 days. You also generally need to reinvest the proceeds and replace the debt or add cash to avoid taxable “boot.”
Bottom line: cash flow helps you hold a rental, while appreciation and principal paydown can build equity for future choices. Both can be useful. The right approach is the one that leaves room for real expenses, changing markets, and your own long-term plan.
If you are looking at a rental purchase, a cash-out refinance, or a plan to use equity for your next property, it helps to see the payment and financing options before you make a move. I can help you look at the mortgage side in plain English. Need financing for an investment property? Get a free mortgage rate quote today!
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
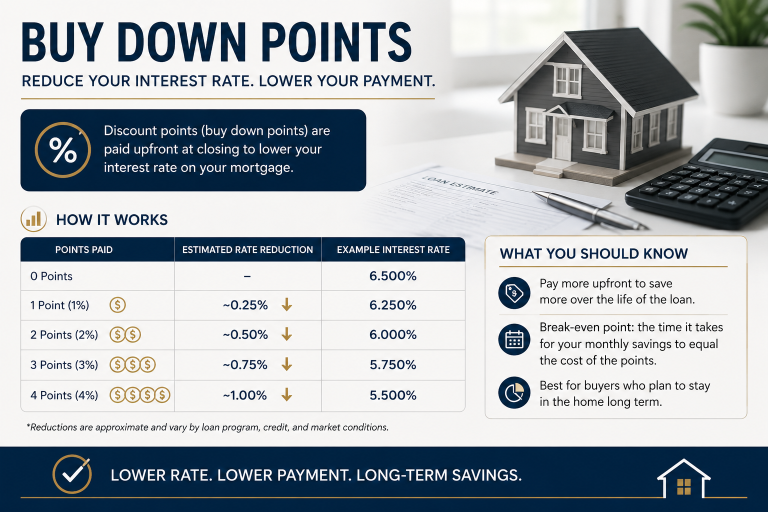
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
Do You Pay Gift Taxes When Buying a House? What Homebuyers Need to Know
One of the most common questions we hear from homebuyers has nothing to do with…
VA Tidewater: What Every Veteran Homebuyer Should Know
If you’re using a VA loan to purchase a home, you may hear the term…
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!