
When to Refinance Your Mortgage: Key Factors for Lowering Costs
If you’ve bought a home recently or are considering lowering your mortgage rate, knowing when to refinance can make a significant financial difference. Many homeowners are looking for opportunities to reduce monthly payments or eliminate private mortgage insurance (PMI). Here are essential guidelines to help you determine if refinancing is the right move.
1. Interest Rate Savings
One of the primary reasons to refinance is to secure a lower interest rate. A general rule of thumb is that if you can lower your rate by at least 1%, it may be worth considering. For example, if your current rate is 7.5%, refinancing to around 6.5% could save you significantly each month. Remember, the larger your loan balance, the more substantial the monthly savings. For loans of $500,000 or more, even a 0.75% rate reduction can create noticeable savings due to the loan size.
2. Eliminating PMI
If your current mortgage includes PMI, you might benefit from refinancing once you’ve built enough equity in your home. In many cases, refinancing with 90% loan-to-value and good credit enables you to eliminate monthly PMI by opting for single-pay mortgage insurance. This one-time upfront payment can often be rolled into the loan or paid at closing. If it removes $200 or more per month, it’s worth evaluating for overall cost reduction and improved cash flow.
3. FHA Streamline Refinance
For homeowners with FHA loans, an FHA streamline refinance is an option. Keep in mind that many FHA refinances may require additional cash due at closing, as per the FHA’s requirements. The amount is based on unused mortgage insurance premiums, which often require funds at closing to complete the transaction. However, this option can still be valuable if it leads to a lower monthly payment.
4. Debt Consolidation
Refinancing can also be an excellent strategy for consolidating debt. By using home equity to pay off high-interest debt, you can reduce your overall monthly expenses. This approach not only helps lower your total outflow but also enhances financial affordability by streamlining payments into a single, often lower-cost, mortgage.
5. Considering Cash-Out Refinances vs. HELOCs
If you’re considering cashing out for home improvements, compare a cash-out refinance with a home equity line of credit (HELOC). HELOCs often carry higher interest rates, ranging from 8-10%, which may negate the benefit of your lower-rate first mortgage. It may be wise to consolidate both into a single mortgage to avoid the long-term expense of holding a high-rate HELOC alongside a low-rate first mortgage. With refinancing, even if rates are slightly higher now, refinancing in the future at a lower rate may allow you to secure better terms in a single loan, benefiting you both now and in the long term.
In conclusion, refinancing depends on your goals, such as reducing monthly payments, consolidating debt, or eliminating PMI. While interest rates vary, the right refinance can position you financially for both current savings and future flexibility.
Looking to get a mortgage? Get a no-cost rate quote today!
Share:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
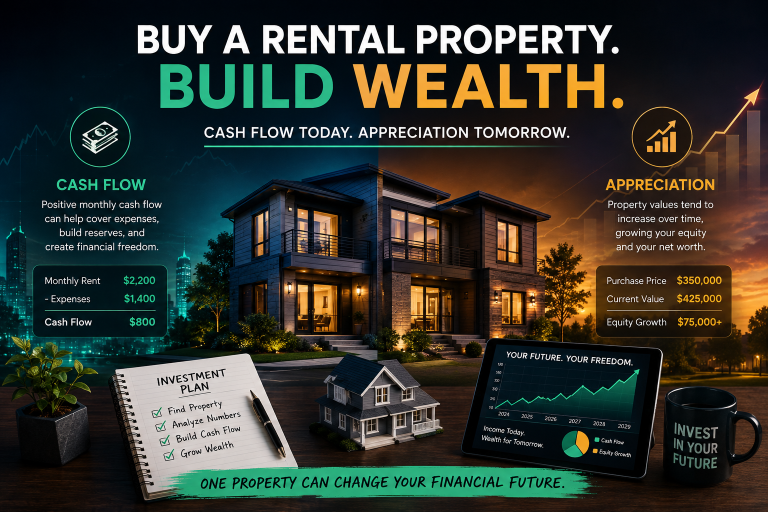
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
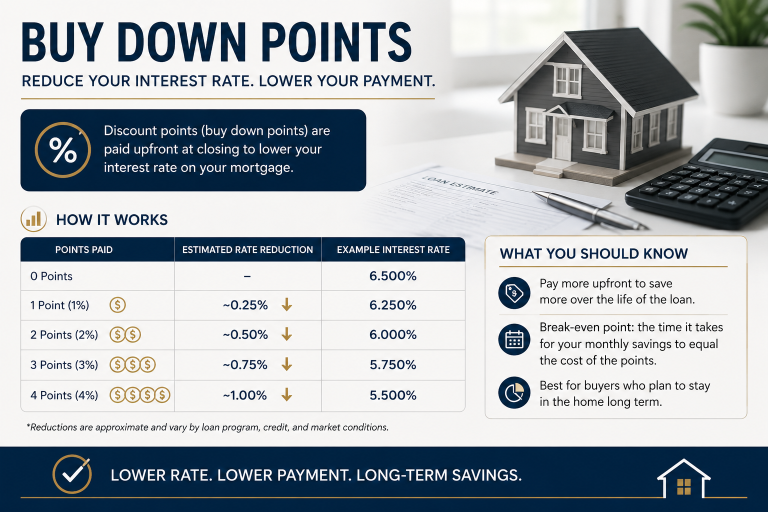
Rate Buydowns in Sonoma County: What Buyers Need to Know in 2026
Rate buydowns can lower a Sonoma County home payment, but temporary and permanent options work very differently. Learn what to compare before you commit.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!