
Want to be 100% liable for someone else’s mortgage? Then cosign for them and you’ll be just as financially accountable for repaying the obligation as they are even though you are cosigning to simply assist the other party. When you cosign on a big-ticket item like a home loan, you are in essence lending your future income and credit for the benefit of someone else’s debt. Doing s,o requires meticulous consideration to every detail of the terms, as well as a potential exit strategy.
Home Loan Co-signing Facts:
Relationship between parties doesn’t matter
The relationship between you and the primary borrower taking out the loan doesn’t matter as long as it’s fully explained and accurately documented. In most cases, cosigning occurs between immediate family members or blood relatives e.g. grand parents cosign for their grand kids to buy their first home.
You future chances are shaped by someone else’s choices
So you helped your sister purchase a home a few years ago by cosigning for them. They have fallen on tough times and have not able to make their mortgage payment obligation reflecting in a negative credit report rating. This negative credit rating subsequently, reports on your credit report as well, you have just as much obligation on that person’s liability as they do.
*Remember responsibility to make timely payment per the mortgage note- no matter how title is held-is still 50/50 between all parties.
Perpetual Attachment
All parties are conjoined on the debt.
Only 2 Ways Out
The person who you cosigned for will have to pay off the mortgage by means of refinancing you off the mortgage or by selling the property which pays off the note and releases all parties from the obligation to repay.
All parties occupying the home as primary residence
You don’t have to reside in the property you are co-signing for, referred to as a non-occupant co-applicant. However, if all parties purchase and live in the house as their primary residence there is a greater level of clarity of financial status amongst the borrowers which does mitigate potential issues down the road cosigning could otherwise cause.
Potential Tax Consequences
If the debt is settled, you could have tax ramifications as the settled amount in full could be taxable in that calendar year.
Co-signor has limited borrowing ability on future obligations
Planning to go take out another home loan? Your ability to get another loan, another credit card, another car loan etc. will be reduced to the extent of how much of your income and liabilities is being used for the obligation you originally cosigned for.
*Caveat to the rule-if you can provide a 12 month history of someone else making a payment on an obligation you cosigned for, most of the time the obligation, you cosigned for can be omitted which would improve borrowing ability.
What cosigning means
It means you are applying for credit by virtue of providing income, credit worthiness, payment liabilities and assets for the purposes of procuring a mortgage. People cosign for other people to help them secure loan financing not knowing the full extent of what cosigning does for the long-term prospectus of future credit.
Loans are made against income. Monthly liabilities erode income. Total liabilities are offset with income.
*Mortgage Tip: Two alternatives to cosigning that substantially help someone else include: providing gift monies for a down payment and/or paying off someone else’s consumer debt, both of which, improve borrowing ability as loans are made against income.
If you are trying to get out of someone else’s mortgage payment, or trying to get a mortgage, contact us online today. Start by getting a complementary mortgage rate quote for your loan scenario.
Share:
Posted in:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
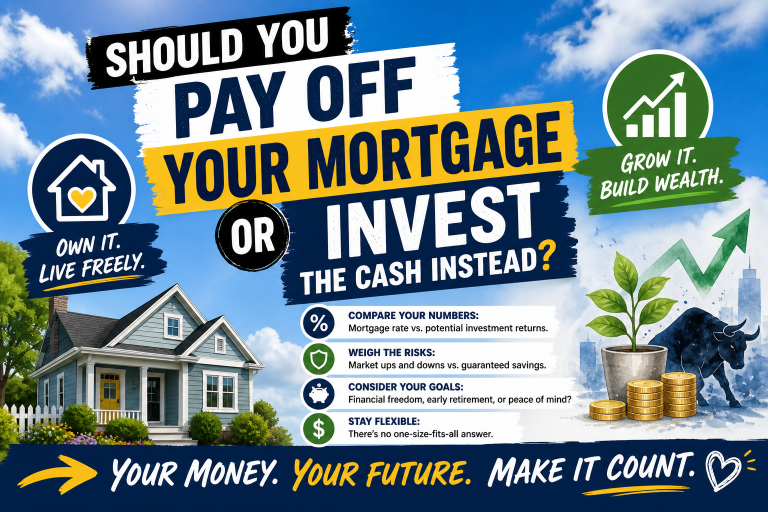
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
Should You Consider an Adjustable-Rate Mortgage? Who Is an ARM Appropriate For?
An adjustable-rate mortgage can save money for the right borrower, but only when the initial savings, timeline, and future payment risk all fit the plan.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!